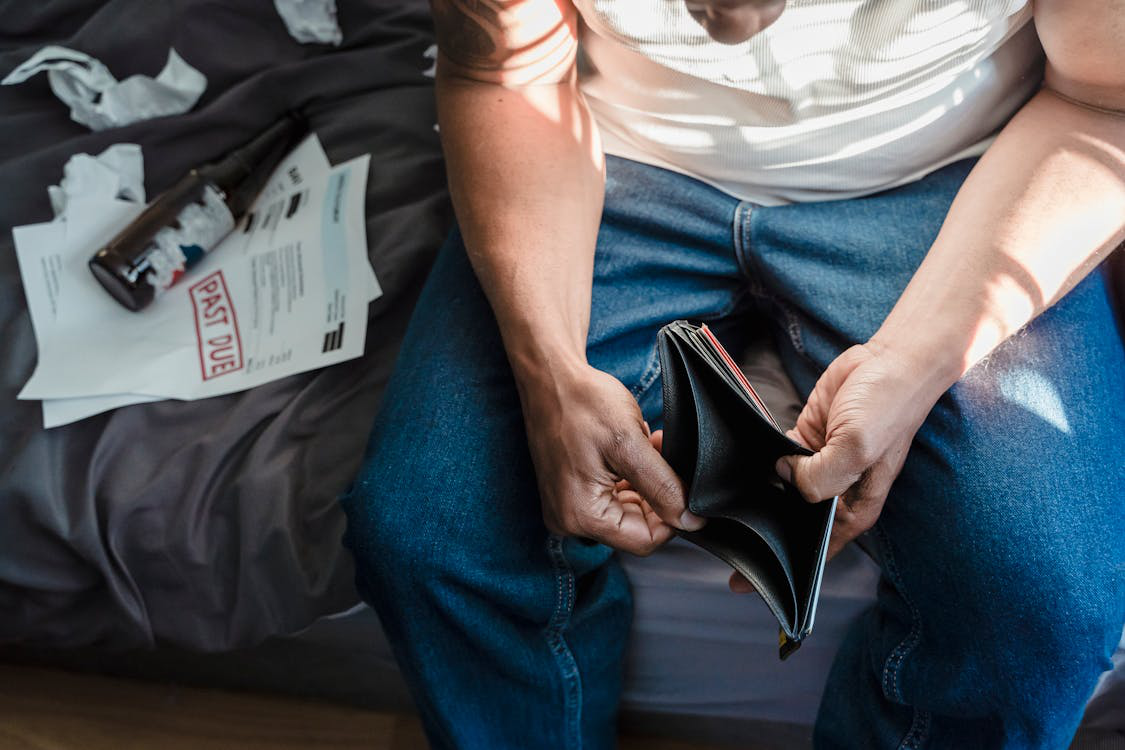
Financial obligations can be manageable when income is steady, and expenses remain predictable. But circumstances can change. Medical bills, reduced income, rising living costs, credit card balances, tax obligations, or unexpected expenses can make keeping up with payments increasingly difficult.
When monthly bills consistently exceed available income, simply trying to “catch up” may no longer solve the underlying problem. Recognizing when financial pressure has become unsustainable can help individuals evaluate their options before making decisions that may have lasting consequences.
Signs Keeping Up With Payments Is Becoming Unsustainable
Missing one payment does not necessarily indicate a serious financial crisis. However, repeated difficulties may signal that a larger problem is developing.
Common warning signs can include using one credit card to pay another bill, making only minimum payments without reducing balances, postponing essential expenses to pay creditors, falling behind on medical or tax debt, or receiving repeated collection notices.
When keeping up with payments requires continually shifting debt from one place to another, it may be time to look closely at the overall financial picture rather than focusing only on the next due date.
Understand Which Debts Require Immediate Attention
Not every debt has the same consequences or legal implications. Credit card debt, medical bills, tax obligations, secured loans, and other liabilities may need to be approached differently.
Before making a major financial decision, consider creating a complete list of debts, balances, interest rates, monthly payments, and collection activity. Understanding where the money is going can make it easier to identify which obligations are creating the greatest financial strain.
If collection activity has escalated or a creditor has filed a lawsuit, speaking with a debt relief attorney can also help you understand your legal options and determine what steps may be appropriate.
Be Careful About Taking On More Debt
When cash is limited, taking out another loan or relying on additional credit can seem like a quick solution. However, new borrowing may only move the problem forward while adding interest, fees, and another monthly obligation.
Before using retirement funds, selling important assets, consolidating debt, or borrowing more money, consider how the decision could affect your long-term finances. A short-term solution is not always the most effective long-term strategy.
When Should You Consider Bankruptcy?
Bankruptcy is not automatically the right answer whenever debt becomes difficult to manage. Depending on the circumstances, budgeting changes, negotiations, or other forms of debt relief may provide a workable path forward.
However, when those approaches are not realistic or sufficient, bankruptcy may be a better approach. Consulting a bankruptcy lawyer can help you understand whether Chapter 7 or Chapter 13 bankruptcy may apply to your circumstances, what debts may be addressed, and what you should consider before filing.
Getting legal guidance before making major financial moves can also help you avoid decisions that could complicate a future bankruptcy case.
Explore Your Options With The Law Office of Joel Gonzalez
If keeping up with payments is no longer realistic, you do not have to make major financial decisions without understanding your legal options. The Law Office of Joel Gonzalez is a respected debt relief law firm in Corpus Christi handling debt collection lawsuits and matters involving credit card debt, medical debt, tax relief, repossession, and bankruptcy.
Attorney Joel Gonzalez practices primarily throughout the Southern District of Texas, including Corpus Christi, Houston, Victoria, McAllen, Laredo, and surrounding communities. He works diligently to defend his clients’ rights and help them evaluate practical paths forward.
Contact our bankruptcy attorney in Corpus Christi to discuss your circumstances and learn which debt relief options may be available to you.